If you’re buying your own health insurance in Maine, you’re doing it without an HR department or anyone whose job it is to sit down and explain the plan to you. For most people the hard part isn’t the paperwork. It’s the choosing.
Where Maine plans come from
CoverME.gov is Maine’s health insurance marketplace, run by the state itself rather than by the federal government. Every plan sold there covers the same set of essential benefits, and no carrier can turn you down or charge you more because of a health condition.
You can also buy an individual or family plan directly from an insurance company, off the marketplace. The difference is financial help, which is only available on plans bought through CoverME.gov. If your household is likely to qualify, that’s where you want to be.
The carriers offering individual coverage here are changing for 2027, and one is leaving the state. If you already have a plan, read When your plan or your carrier goes away read our plan changes page first.
When you can enroll
Open enrollment for 2027 coverage runs November 1, 2026 through January 15, 2027. Inside that window you can start a plan, switch plans or change carriers for any reason at all, with no questions asked about your health.
Outside that window you need a qualifying life event, which is a specific change in your life that opens an enrollment period just for you. Marriage, divorce, the birth or adoption of a child, a move, and the loss of coverage you already had all count. So does a carrier leaving the Maine market, because that counts as losing your coverage.
Maine adds one that most states don’t. Pregnancy is a qualifying life event here, so a pregnant Mainer can enroll without waiting for open enrollment to come back around.
There’s one more Maine specific way in. Under Maine’s Easy Enrollment program you can indicate on your state income tax return that you’re uninsured and would like help getting covered, and the state follows up with you about your options.
What Maine requires every individual plan to cover
Maine law puts two things in front of the deductible on individual plans, and it changes how you use your coverage in January.
Your first primary care visit of the year and your first behavioral health visit of the year must be covered in full, with no deductible and no coinsurance. Visits two and three require only a copay.
So if you’ve put off a physical, or a first appointment with a counselor, because you assumed you’d pay full price until the deductible was met, that isn’t how it works here.
Financial help, described honestly
The premium tax credit is a discount applied to your monthly premium, paid on your behalf so you never front the money. Whether you qualify depends on your household income, your household size, and whether you have access to other coverage such as a plan through a job or a spouse’s job.
Some households also qualify for a second kind of help that lowers deductibles and copays. Eligibility for that one is narrower. Tax credits and cost sharing reductions are determined by your tax household’s Modified Adjusted Gross Income (MAGI).
MAGI is your Adjusted Gross Income (AGI), plus any tax-exempt foreign income, tax-exempt Social Security benefits and tier 1 railroad retirement benefits, tax-exempt interest. However, MAGI excludes Supplemental Security Income (SSI).
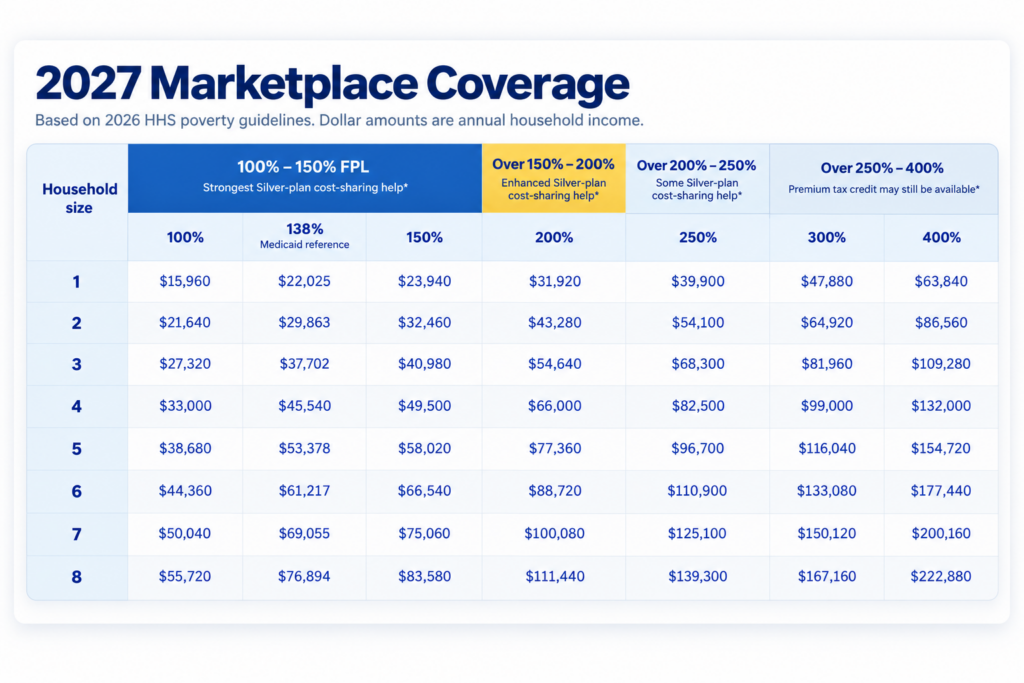
We can run your numbers and tell you what you’re likely to qualify for, including when the answer is nothing.
The two questions that decide it
Premium is the number people shop on, and it’s the wrong place to start.
The first thing that decides a plan is the network, meaning the doctors, hospitals and specialists that have agreed to the plan’s pricing. Two plans from the same carrier can have very different networks, and a plan that excludes the practice you’ve used for years is a bad plan for you at any price.
The second is the drug list, sometimes called the formulary, which is the list of medications the plan covers and what tier each one sits on. A plan can cover your prescription, cover it at a tier that costs you a great deal, or not cover it at all.
So before we talk about premium, we’ll want these from you:
- The doctors, specialists and hospitals you want to keep, by name and practice
- Every prescription in the household, with the dosage
- Your residential zip code and county
- The ages of everyone who needs coverage
- Your best estimate of household income for the coverage year
Since 2023 Maine has run its individual and small group markets as a single merged risk pool, which is unusual and is why coverage here prices differently than in most states, and we explain that on our fully insured small group page.
Call us at (207) 304-2909 or request a review. We’ll narrow the field to the plans that actually cover your doctors and your prescriptions, then compare cost across what’s left.
BEST PRICE GUARANTEE
As always, our services are 100% FREE and there is no extra cost or mark-up. Whether you get your health insurance through us, another agent/broker or directly from the insurance carrier or CoverME.gov, you’ll pay the exact same monthly premium for the same plan, so you can rest assured that you’re getting the best available price.