For Maine Employers
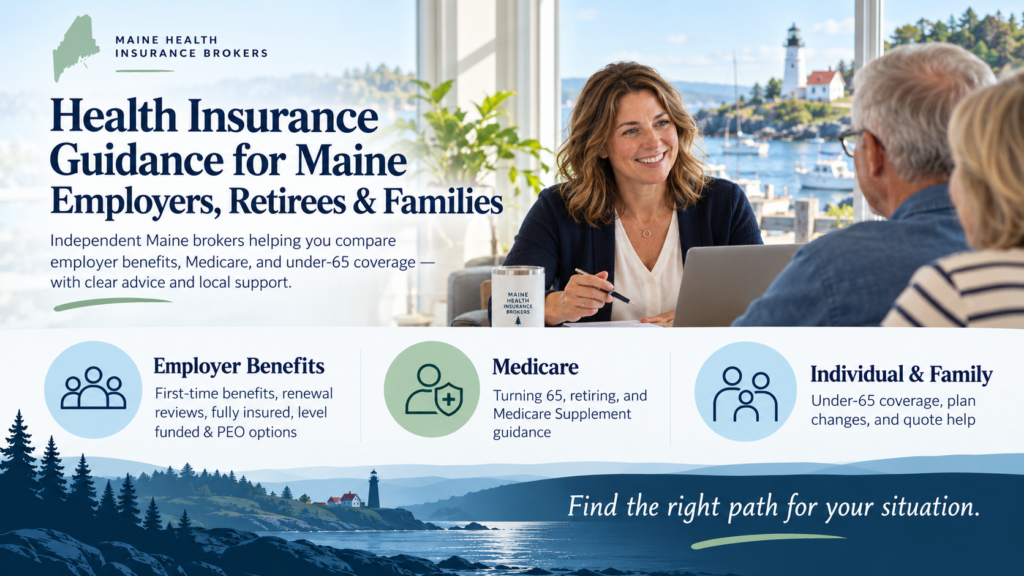
Much of what we do is employee benefits for Maine companies. A small employer in Maine is one with 50 or fewer eligible employees, counting at least one employee who isn’t the owner or the owner’s spouse. Employees averaging 30 or more hours a week are eligible, coverage is guaranteed issue, and there are no pre-existing condition exclusions.
From there the real decision is how the plan is funded. Fully insured small group, level funded, or a PEO, which is a professional employer organization that becomes the co-employer of record for payroll, HR and benefits. They price differently, they carry different risk, and one of them is usually clearly better for a company your size.
Maine also merged its individual and small group markets in 2023, which is why a small group quote here behaves differently than in most other states. \
Employer clients also get Mineral, the HR compliance platform we provide at no cost to our benefits clients. It includes an employee handbook builder and policy library, live HR advisors you can ask questions of, and alerts when employment law changes.
What changed in Maine for 2027
The Maine Bureau of Insurance approved a 14.8 percent average rate increase in the individual market for 2027 and a 13.5 percent average in small group. Both came in below what the carriers asked for, which was 16.8 percent and 15.7 percent. An average isn’t a number anyone actually pays, though. What happens to your premium depends on your plan, your age and where in Maine you live.
The carrier lineup is moving too. Mending Health, formerly Taro Health, is leaving the Maine market after 2026. Anthem is discontinuing its individual PPO plans on CoverME.gov, Maine’s own marketplace for individual and family coverage, while continuing to sell PPO off the marketplace and to small groups.
We’re licensed Maine brokers, and we’ll tell you plainly what those changes do to your plan or your company’s plan, and what your options are.
Find your situation
-
- Offering employee benefits for the first time.
- Your renewal came in higher than you expected.
- Deciding between fully insured, level funded and PEO.
- You’re turning 65 soon.
- You’re retiring off an employer plan.
- Your individual plan or carrier is going away.
- You want to look at other individual/family plans.
Medicare and coverage before 65
Maine gives people on Medicare Supplement coverage switching rights that most states don’t. Every insurer selling Medicare Supplement coverage here has to designate one month each year as a guaranteed issue period for Plan A, and Maine policyholders who’ve kept continuous coverage have more room to change plans than they usually realize.
If you’re under 65 and buying your own coverage, open enrollment for 2027 runs November 1, 2026 through January 15, 2027. Outside that window you need a qualifying life event to trigger a 60 day Special Enrollment Period, and in Maine pregnancy counts as one.
How we work
We’re independent, so we’re not carrying one carrier’s bag. We look at what’s actually available to you in your county, we say which option we’d pick and why, and we tell you when the honest answer is to stay where you are.
You’ll talk to a person who’s licensed in Maine and who’ll still be the one answering the phone next year if something goes wrong with a claim or an invoice.
Talk to a Maine broker
Pick the conversation that matches what you need. Employers, request a Benefits review. If you buy your own insurance or are interested in doing so, request a Medicare review or an Individual and family review, or give us a call at (207) 304-2909.