The Maine Guaranteed Access Reinsurance Association, MGARA, pays 60 percent of eligible claims in Maine’s merged individual and small group market for 2026. It is a large part of why Maine fully insured premiums are not higher than they are.
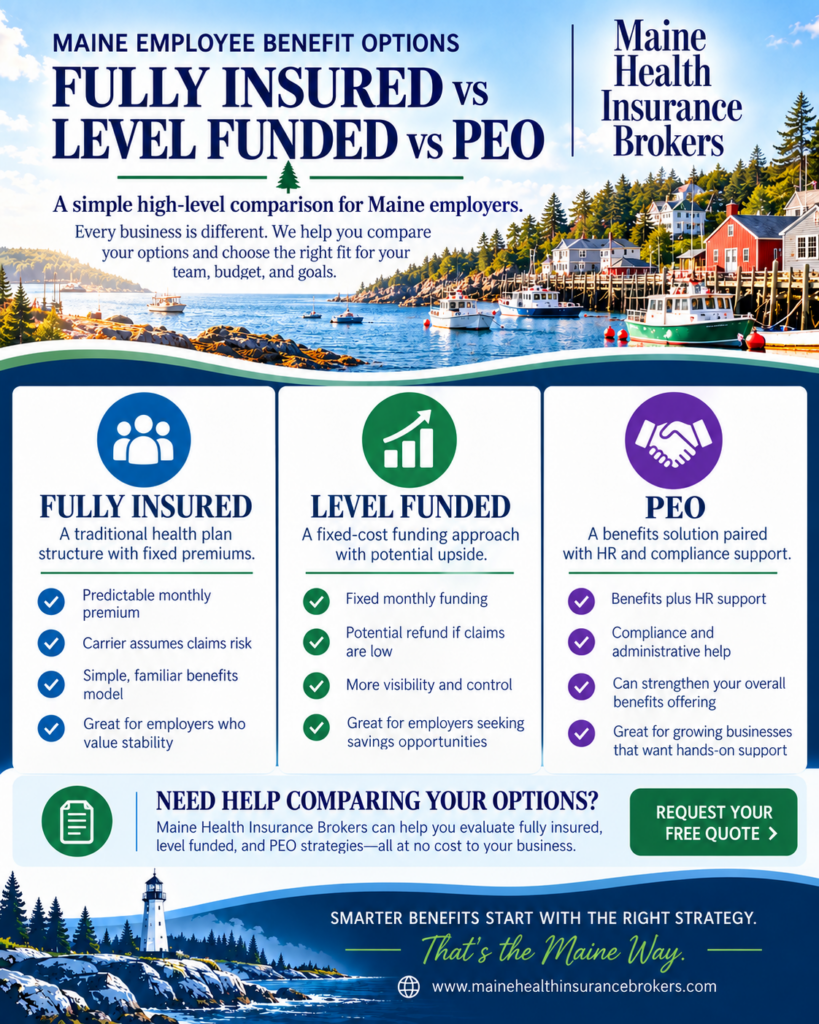
The comparison
| Fully insured small group | Level funded | PEO | |
| Who carries claims risk | The insurance carrier, entirely | Your company, up to the stop loss limits | The PEO’s plan, across its whole client pool |
| How the rate is set | Filed with and approved by the Maine Bureau of Insurance. Age, tobacco use and geography only | Projected off your own group’s health, through questionnaires or claims history. Not filed with the Bureau | Usually a percentage of payroll or a per employee per month fee, plus the benefit cost. Not a filed insurance rate |
| Health questions on your employees | None. Guaranteed issue, no pre-existing condition exclusions | Yes, and your group can be rated up or declined | Depends on the PEO and the plan offered |
| Can surplus come back to you | No | Yes, if claims run under projection. Terms vary by carrier | No |
| Reinsurance behind the pool | Yes, MGARA at 60 percent of eligible claims for 2026 | No | No |
| Administrative burden on you | Moderate. Enrollment, changes, billing | Moderate, plus claims reporting to read and act on | Lowest. Payroll, taxes, workers comp and HR move to the PEO |
| What happens at renewal | A filed rate change. The Bureau approved a 13.5 percent average small group increase for 2027 | A new projection built on your last twelve months of claims, plus a surplus settlement | A contract renewal covering both service fees and benefit cost |
| How hard to reverse | Easiest. It is an enrollment | Moderate. You return to underwriting, and late claims settle after you leave | Hardest. Payroll registration, workers comp and benefits all have to be re established |
| Tends to fit | 50 or fewer eligible employees, mixed ages, owners who want one predictable number | Younger, healthier, stable groups whose owner can fund a bad year | Owners doing payroll and HR themselves, or growing faster than the back office |
Reading the table
If a bad claims year would genuinely hurt your company, fully insured is the answer and the rest of the table is interesting rather than relevant. You are buying the carrier’s willingness to be wrong about your group, and in Maine you are buying it inside a regulated, reinsured pool that a small employer cannot get to any other way.
If your group is young and healthy and your company could absorb a rough twelve months, level funding is worth quoting. The surplus is the reward for taking the risk back. Just understand that the same underwriting that earns you a lower projection can also decline you, and that the protections you leave behind are guaranteed issue and filed rates.
If the problem you are actually trying to solve is that you are running payroll at 9pm and hoping you handled Maine Paid Family and Medical Leave correctly, neither of the first two columns fixes that. A PEO does, and the pooled purchasing is a second benefit rather than the main one.
Reversibility matters because you will not get this exactly right the first time. Changing carriers is an enrollment. Leaving a PEO is a project.
Renewal mechanics matter because they determine what a bad year costs you later. A filed rate change lands on the whole small group market. A level funded reprojection lands on you specifically.
Group size is the weakest dimension of any comparison like this, because the honest answer is that it depends on your ages and your claims more than your headcount.
Request a Free Employer Benefits Review today.
Questions to answer before you choose
If you can answer these questions up front, this saves a lot of time in narrowing the options:
- How many of your employees average 30 or more hours a week, and what are their ages?
- Who in your company currently runs payroll, onboarding and benefits changes, and how many hours a week does it take them?
- Are you currently tracking earned paid leave and Maine Paid Family and Medical Leave contributions correctly, and do you know it or assume it?
- Do your employees care more about a lower premium or a broader network, and have you ever asked them?
- Are you aware of any serious health issues for your enrolling employees?
Bring your answers and a census, and we’ll quote the models that make sense for your company.