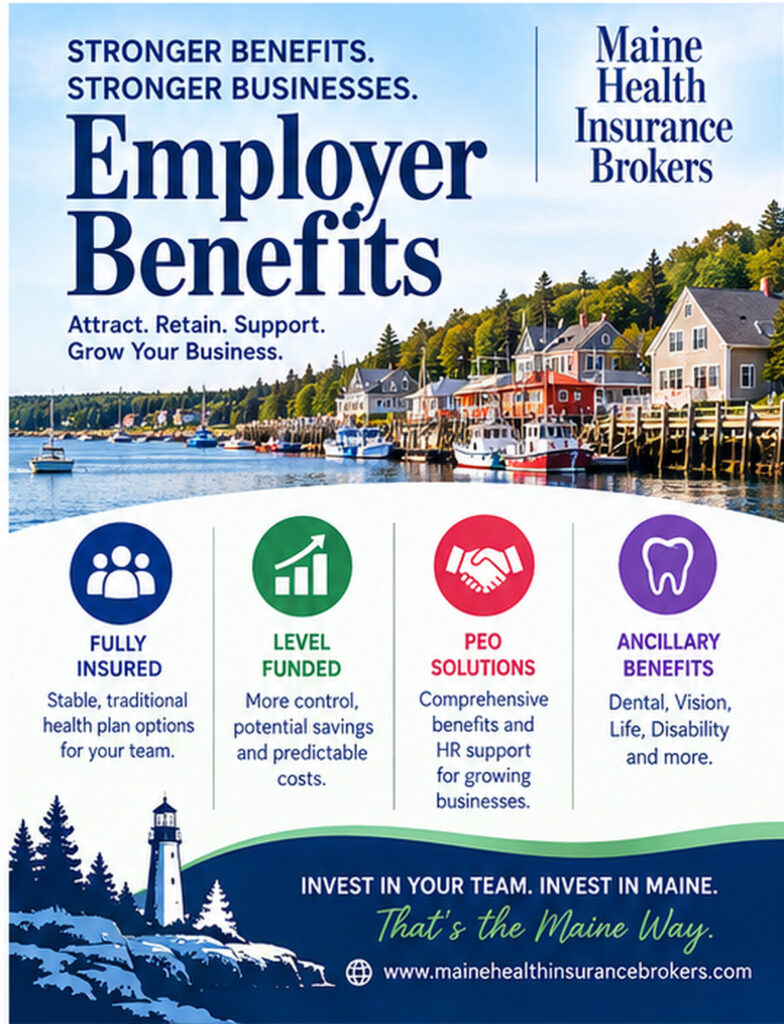
There are three ways to fund a medical plan here, and most of the other decisions follow from that one. Fully insured, level funded, or a Professional Employer Organization, better known as PEO. Each puts claims risk in a different place, sets your rate a different way, and asks a different amount of administrative work from you.
Nobody should pick one because it sounds modern or because a payroll company brought it up first. Get professional guidance for your company’s employee benefits.
Fully insured small group
You pay a monthly premium to an insurance carrier and the carrier owns every dollar of claims risk. If your employees have a terrible year, your premium doesn’t move mid year. If they have a great year, you don’t get anything back.
In Maine this is the most regulated of the three. Small group rates are filed with and approved by the Maine Bureau of Insurance, and since 2023 small group plans sit in the same risk pool as individual coverage, which is unusual and which changes how your quote behaves. We explain that in full on the fully insured page.
This tends to fit companies with 50 or fewer eligible employees who want a predictable number they can budget, who have an older or mixed-health workforce, or who simply don’t want to think about claims at all.
One Maine detail worth knowing before you shop: Anthem is discontinuing individual PPO plans on CoverME.gov for 2027, while continuing to offer PPO coverage to small groups. If a broad network matters to your employees, the small group market may be where it still lives.
Level funded
You pay a fixed monthly amount that looks and feels like a premium, but part of it is set aside to pay your own employees’ claims. If claims come in lower than projected, your company can receive money back at the end of the year. If they come in higher, stop loss coverage is what protects you, and the carrier will want to know your group’s health before it quotes.
This tends to fit younger, healthier groups with low turnover and an owner who can tolerate a year that doesn’t go their way. It is usually not the right call for a group that would be hurt by one bad claims year, and it is not available to every group at every size. Usually you need to maintain a minimum of 10 employees enrolled year around.
PEO
A PEO becomes a co-employer of your staff for payroll, tax, workers compensation and benefits purposes. Because your employees join a much larger pool, you can often reach plan designs and rates a company your size could not get on its own. That pooled purchasing argument is true of a PEO and it is not true of the other two.
It tends to fit owners who are spending real hours on payroll and HR, companies hiring faster than their back office can keep up, and anyone worried about getting Maine Paid Family and Medical Leave administration right.
Dental, vision, life and disability
Medical is the where most of the costs are, but the rest are important to employees too.
Dental and vision are the two benefits people ask about first, and they are inexpensive enough that many first time employers add them right away. Group life is often offered as a flat benefit amount with a guaranteed issue level. Short and long term disability replaces part of an employee’s income when they can’t work, which matters more in Maine now that Paid Family and Medical Leave covers only part of a wage and only for a limited number of weeks.
These lines can be quoted with your medical plan or added later. You don’t have to buy them all at once.
What working with us across a plan year looks like
Quoting comes first. We gather a census, your current plan if you have one, and your renewal if you’ve received it, then bring back options across whichever funding models actually make sense for your group rather than all three for show. Get a free employer benefits quote.
We do the heavy lifting, including any employee meetings and directly answering the questions employees would rather not ask you.
Through the year, your employees call us. Denied claims, ID cards, a spouse added after a wedding, a doctor who says they’re out of network. That work doesn’t land on your desk.
At renewal we review the increase against what else is available, and we tell you when staying put is the better answer. The Maine Bureau of Insurance approved a 13.5 percent average small group increase for 2027, so most Maine employers will be having this conversation.
For compliance and HR questions beyond insurance, employer clients get Mineral, the HR platform we provide through Gain Financial Services, Inc.
Start by comparing the three funding models side by side, then book a working session and we’ll build the quote around your actual census.